
Global capital. African potential.
Tedoforo Capital connects global investors with African businesses in sports, entertainment, technology and the essential services that support them. Our proposed flagship fund, ASET, combines specialist fund investments with direct ownership to support business growth and long-term value creation.
The investment case
Invest in the businesses behind Africa’s potential.
Our investment thesis connects participation in sport, cultural enterprise and digital access with education, healthcare and enabling infrastructure. We seek businesses with identifiable customers, recurring demand and a credible path from growth to cash generation.
The platform
A common approach to governance, capital formation, partnerships and portfolio development. Each future fund will have its own defined mandate and identity.
The first fund
African Sports, Entertainment and Technology: the flagship strategy connecting talent, culture and digital enterprise with education, healthcare and enabling infrastructure.
Portfolio approach
50% / 50%
Initial target: specialist funds and direct investments.
Initial geographic focus
Three core markets
South Africa, Morocco and Kenya.
Value creation
Build, grow, realise
Strengthen operations, expand proven businesses and plan exits from entry.
ASET investment strategy
Connected sectors. Commercial foundations.
ASET stands for African Sports, Entertainment and Technology. The strategy invests across these sectors and the schools, healthcare businesses, digital systems and infrastructure that enable them.
The connection must be commercial: shared customers, distribution, facilities or technology. Every investment must have a substantive African connection and sound economics in its own right.

Participate
Sport & performance
Academies, school and community sport, participation businesses, coaching, fitness, rehabilitation and sports medicine. Build recurring income and lasting participation beyond individual events or player transfers.
Our Investment Lens
Recurring participation. Sustainable revenue. Measurable outcomes.
Create
Entertainment & culture
Music rights, creator services, production, distribution, ticketing and live experiences. Verify intellectual property, contracted revenues, audience conversion and cash collection.
Our Investment Lens
Owned rights. Repeatable distribution. Cash collected from audiences.
Connect
Technology & access
Payments, enterprise systems, digital delivery and connectivity. Telecommunications and broadband can serve schools, clinics, communities and venues where paying demand supports sustainable returns.
Our Investment Lens
Paying users. Useful products. Reliable access.
Learn
Schools & EdTech
Primary and secondary schools, vocational pathways, teacher training, administration and learning technology. Test affordability, fee collections, retention, learning outcomes and safeguarding.
Our Investment Lens
Affordable education. Strong collections. Better learning outcomes.
Thrive
Primary care & HealthTech
Primary-care networks, prevention, diagnostics, patient systems and performance healthcare. Prioritise care quality, clinician capacity, sustainable payer models and responsible handling of patient data.
Our Investment Lens
Quality care. Credible payers. Sustainable clinical delivery.
Enable
Infrastructure & hospitality
Contracted facilities, power and connectivity, together with selective sports- and entertainment-linked hospitality. Demand, utilisation and cash generation must stand beyond a single event or subsidy.
Our Investment Lens
Contracted demand. Year-round utilisation. Disciplined capital spending.

The torch is already litCapital carries it further
Our investment approach
Two ways to invest. One standard of discipline.
Specialist funds
50%
Access experienced managers with relevant sector knowledge, local execution and attributable realised results. Assess governance, fee layering, portfolio overlap, reporting and the ability to return capital within ASET’s life.
Direct investments
50%
Growth capital, selective acquisitions and buyouts. Back capable operators, secure meaningful governance rights and build practical value-creation plans, with follow-on capital for proven businesses.
Build value before expanding
Strengthen finance, procurement, technology, management and reporting. Expand proven operating platforms across borders only when customer economics and local execution support it.

Commercial entry gates
Reconcile earnings to cash. Verify ownership, licences, customers and management. Stress-test currency exposure, costs and collections.
Exits from the outset
Identify credible strategic buyers and financial sponsors during underwriting. A listing is an option to evaluate, never an assumed source of liquidity.
Partnerships with evidence
PPPs require enforceable rights and payment security. Grants may support access, training and pilots; unawarded grants are modelled at zero. No partnership is represented as secured.
A selective African footprint
A focused entry. A measured expansion.
Complementary regional operating bases, followed by measured expansion. These are sourcing priorities shaped by mandate fit, execution, currency recovery and credible exits—not fixed capital allocations.
Core 1–3
Expansion 4–5
Later 6–10
Numbers 1–10 show ASET’s country priority ranking. Select a number or highlighted country to explore it. Colours show rollout phases, not an investment score. Map: Natural Earth / world-atlas; boundaries shown for geographic orientation.
Phase 1 / Core / Priority 1
South Africa
Acquisition and operating anchor
Build shared operating capabilities through established healthcare, education, performance and technology businesses. Existing sponsor relationships support origination.
64.75m
Population, 2025
$427.18bn
Nominal GDP, 2025
78.4%
Internet use, 2024
41 / 100
CPI, 2025, higher is cleaner
Entry discipline
Reconcile earnings to cash, verify licences and model currency and infrastructure pressures.
Phase 1 / Core / Priority 2
Morocco
North African sports and service platform
Combine sports services, school-linked academies, rehabilitation, event technology and content with strong digital access.
38.43m
Population, 2025
$182.37bn
Nominal GDP, 2025
91.2%
Internet use, 2024
39 / 100
CPI, 2025, higher is cleaner
Entry discipline
Require sustainable utilisation beyond major events and verify land, concessions and capital recovery.
Phase 1 / Core / Priority 3
Kenya
East African digital and service delivery
Connect clinic and school networks with software, diagnostics, payments and affordable connectivity. Complements the Southern and North African bases.
57.53m
Population, 2025
$135.94bn
Nominal GDP, 2025
35.0%
Internet use, 2024
30 / 100
CPI, 2025, higher is cleaner
Entry discipline
Prove collections, affordability and offline delivery; stress-test payer exposure and currency.
Phase 2 / Expansion / Priority 4
Egypt
Scale and Arabic-language distribution
Extend education, primary care, diagnostics, ticketing and software into a large domestic market with Arabic-language reach.
118.37m
Population, 2025
$365.25bn
Nominal GDP, 2025
74.6%
Internet use, 2024
30 / 100
CPI, 2025, higher is cleaner
Entry discipline
Secure experienced local management and a documented route for conversion and remittance.
Phase 2 / Expansion / Priority 5
Côte d’Ivoire
Francophone West African base
Build from Abidjan in education, primary care, payments, creator services and connectivity, adding Francophone reach.
32.71m
Population, 2025
$99.77bn
Nominal GDP, 2025
41.4%
Internet use, 2024
43 / 100
CPI, 2025, higher is cleaner
Entry discipline
Verify cash controls, local execution and private collections before extrapolating regional demand.
Phase 3 / Later rollout / Priority 6
Nigeria
Entertainment, payments and technology scale
Develop rights, music, creator distribution and payment platforms, with selective education and healthcare opportunities.
237.53m
Population, 2025
$290.79bn
Nominal GDP, 2025
41.2%
Internet use, 2024
26 / 100
CPI, 2025, higher is cleaner
Entry discipline
A large audience must convert to cash. Stress-test affordability, infrastructure costs and currency recovery.
Phase 3 / Later rollout / Priority 7
Ghana
Selective English-speaking West African platform
Consider school administration, vocational training, primary care, health software and creative-business services.
35.06m
Population, 2025
$114.21bn
Nominal GDP, 2025
72.2%
Internet use, 2024
43 / 100
CPI, 2025, higher is cleaner
Entry discipline
A distinct transaction must justify another regional base; model currency weakness and public-payer exposure.
Phase 3 / Later rollout / Priority 8
Tanzania
Extend proven East African platforms
Expand affordable school and primary-care networks, supported by software, payment collection and Swahili localisation.
70.55m
Population, 2025
$90.14bn
Nominal GDP, 2025
31.2%
Internet use, 2024
40 / 100
CPI, 2025, higher is cleaner
Entry discipline
Validate delivery costs, electricity, connectivity, licences and working capital with a capable local operator.
Phase 3 / Later rollout / Priority 9
Rwanda
Specialist and regional service projects
Explore health and education technology, performance services and training with customers beyond the domestic market.
14.57m
Population, 2025
$16.37bn
Nominal GDP, 2025
31.7%
Internet use, 2024
58 / 100
CPI, 2025, higher is cleaner
Entry discipline
Small market size requires regional demand and economics that do not depend on perpetual sponsorship.
Phase 3 / Later rollout / Priority 10
Senegal
Francophone services with selective entry
Extend a proven Francophone platform through education, primary care, creative services and sports development.
18.93m
Population, 2025
$37.01bn
Nominal GDP, 2025
60.1%
Internet use, 2024
46 / 100
CPI, 2025, higher is cleaner
Entry discipline
Prioritise private collections and exportable services; test fiscal exposure and public-payment risks.
Establish the core
South Africa, Morocco and Kenya provide Southern, North and East African operating bases while focusing initial resources.
Expand to five
Egypt adds scale and Arabic-language distribution. Côte d’Ivoire adds a Francophone West African base.
Extend proven platforms
Nigeria, Ghana, Tanzania, Rwanda and Senegal widen reach as execution capacity, partnerships and commercial economics are demonstrated.
Tunisia, Namibia and Botswana remain reserves. Mauritius is assessed separately as a structuring option. Country figures reproduce the existing country paper: population and nominal GDP 2025; internet use 2024; CPI 2025. Source references and limitations are in the paper.
Proposed fund framework
A framework for long-term investors.
For institutions, family offices and other eligible investors. Fund structure, service providers, eligibility and commercial terms remain subject to final agreement and definitive documentation.

Luxembourg
Proposed closed-ended compartment within the PRISM SICAV-RAIF umbrella, subject to diligence, consents and documentation.
10 years
Proposed term from first close, with up to three one-year extensions under agreed consents.
20% carry
Proposed whole-fund basis after capital return and recovery of losses, fees and expenses. No preferred-return hurdle or catch-up.
Below 2%
Commercial objective for combined recurring investor costs, including both management layers and routine expenses. Feasibility remains to be demonstrated.
Quarterly reporting
Proposed reporting on investments, liquidity, valuations, concentration, fees, impact and exit progress.
Long-term value
No routine redemption rights or promised annual cash yield. Distribution and reinvestment mechanics remain subject to final documents.

Fee approach and matters still to be finalised
The framework proposes a 2% fee on the direct sleeve and 0.8–1.0% to Tedoforo on the fund-of-funds sleeve, with underlying management fees negotiated to 1.0–1.2%. The rates must be paired within an agreed cost budget; the maxima cannot simply be combined. Underlying carry may apply in addition to ASET carry, and formation, transaction costs and taxes require separate disclosure.
The investor overview describes a €50 million minimum raise and €100 million target; the detailed framework leaves fund size open. These remain fundraising proposals to reconcile before external circulation. Fund domicile, appointments, fee bases, investment period, distribution rules and investor consents also require final agreement.
This website is an initial investment concept for discussion, not final offering documentation or an invitation to subscribe. No investment, return, fundraising outcome or launch status is guaranteed.
The founding team
Global relationships. African execution.
A founding team bringing complementary investment, operating and relationship experience.
Mario Carlo Ferrario
Brings international private-equity experience and senior relationships to the proposed platform.

Daniel Ryan
Brings private-equity, investment assessment and portfolio experience to the proposed platform.
Hayet Hammana
Brings asset-management, banking and venture-capital experience to the proposed platform.
Paolo Bertaccini
Brings institutional, sports and public-sector partnership experience to the proposed platform.
Ajay Wasserman
Brings African business-development, investment-origination and execution experience to the proposed platform.
The story behind the name
Carrying the torch on behalf of Africa.
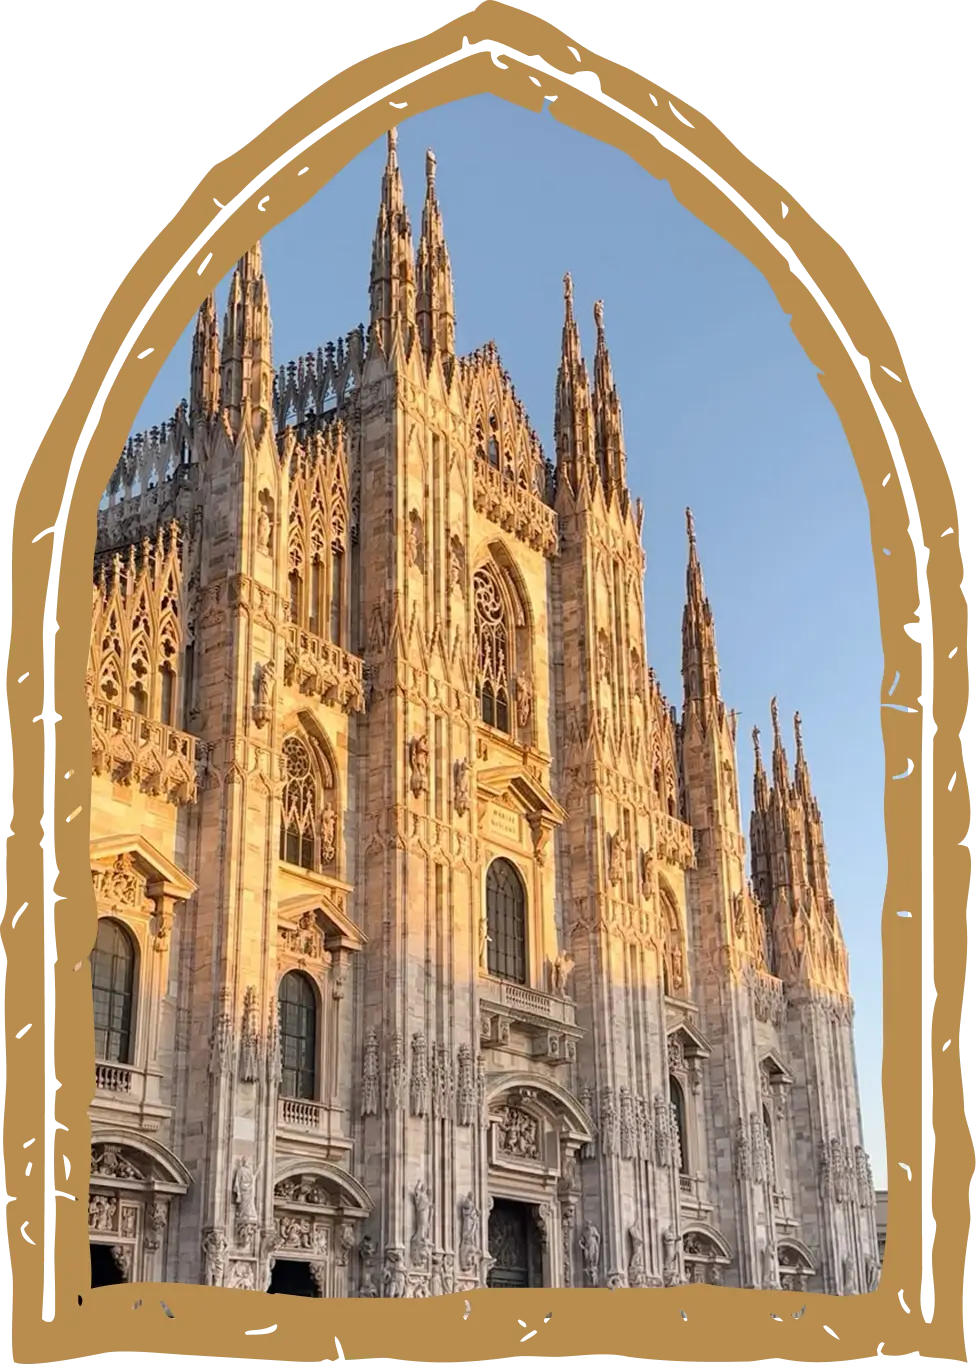
Tedoforo means “torchbearer” in Italian. The brand was inspired by a walk beside Milan’s Duomo on 21 September 2026 and the story of the Spire of Anonymity, honouring unnamed Milanese contributors.
For Tedoforo, the torch recognises the entrepreneurs, workers, athletes, creators and innovators building Africa’s future. The potential is already here. Our responsibility is to connect it with capital, markets and opportunity.
For global investors
Start with the strategy. Explore the detail.
For institutions, family offices and other eligible investors evaluating the proposed ASET fund. Review the investment thesis, geographic priorities and proposed structure in the materials below.
Discussion materials, subject to further diligence and final documentation. Linked documents may require access approval.
Get in touch
Let’s build what’s next.
Whether you’re an investor looking at African growth, a founder building in sport, entertainment or technology, or a partner who wants to work with us, tell us what you have in mind. We read every message.